Case Name: Union of India & Ors. v. The Board of Trustees of the Port of Bombay
Appeal: Civil Appeal No. 4477 of 2010
Neutral Citation: 2026 INSC 919
Date of Judgment: 25.08.2026
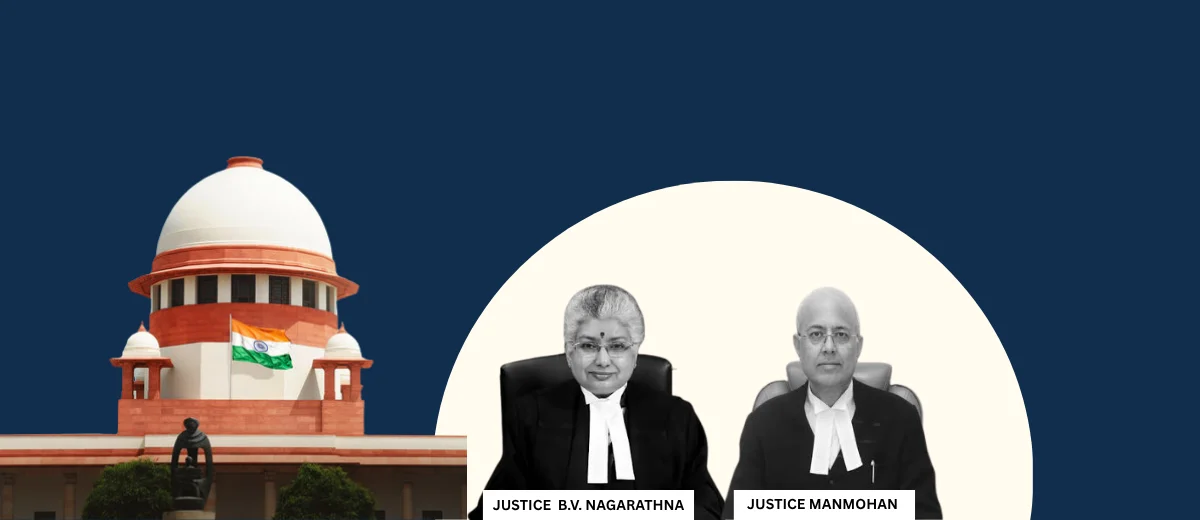
Coram: Hon’ble Mrs. Justice B.V. Nagarathna and Hon’ble Mr. Justice Manmohan
Relevant Statutes and Provisions: Section 13, Section 23 and Section 45(1), Section 45(2) and Section 45(3) of the Customs Act, 1962, Sections 42 and Section 43 of the Major Port Trusts Act, 1963; and Sections 151, Section 152 and Section 161 of the Indian Contract Act, 1872.
(The judgment concerns whether the Commissioner of Customs was empowered under Section 45(1) of the Customs Act to approve the Mumbai Port Trust as the custodian of imported goods, and whether customs duty could consequently be imposed on the Port Trust for goods pilfered while in its custody under Section 45(3), particularly in light of the saving clause under Section 45(1), the non-obstante clause under Section 45(3), and the provisions of the Major Port Trusts Act.)
In this judgment, the Hon’ble Supreme Court examined whether the Notification dated 11.10.2000 issued by the Commissioner of Customs under Section 45(1) of the Customs Act, 1962, approving the Mumbai Port Trust as the custodian of imported goods, was legally valid, and whether liability for customs duty on goods pilfered while in its custody could consequently be fastened upon the Port Trust under Section 45(3). The Court considered the interplay between Sections 13, 45(1), 45(2) and 45(3) of the Customs Act and Sections 42 and 43 of the Major Port Trusts Act, 1963, particularly the saving clause under Section 45(1) and the non-obstante clause under Section 45(3). The Court held that the liability under Section 45(3) is an independent statutory liability towards the Revenue and is distinct from the Port Trust’s civil/bailee liability under the Major Port Trusts Act. Accordingly, the Court upheld the validity of the Notification dated 11.10.2000, while holding that customs duty could not be recovered for pilferage occurring prior to the date of the Notification, as the Port Trust had not been approved as a custodian under Section 45(1) during that period.
FACTS
The respondent, the Board of Trustees of the Port of Bombay (Mumbai Port Trust), is a statutory Major Port Trust constituted under the Major Port Trusts Act, 1963. During 1996–2000, certain imported goods were pilfered while in the custody of the Port Trust. The Assistant Commissioner of Customs issued show-cause-cum-demand notices seeking recovery of customs duty from the Port Trust under Section 45(3) of the Customs Act, 1962. On 11.10.2000, the Commissioner of Customs issued a notification under Section 45(1) of the Customs Act, formally approving Mumbai Port Trust as the custodian of imported goods and making it responsible for the statutory duties under Section 45, including liability for pilfered goods. The Port Trust challenged the orders confirming the customs duty and the 11.10.2000 notification before the Bombay High Court. The High Court allowed the writ petition, holding that under Section 45 (1) of the Customs Act, the recovery of duty in respect of pilfered goods is only from the person approved by the Commissioner of Customs and not from a body of persons constituted under law and entrusted with the custody of goods, namely, the Mumbai Port Trust incorporated under the Major Port Trusts Act. It consequently quashed the notification and the demand orders. Aggrieved by the High Court’s decision, the Union of India appealed to the Supreme Court. The Supreme Court ultimately upheld the validity of the notification under Section 45(1), while the pre-notification demands could not be sustained because no approval under Section 45(1) existed during that period.
ISSUE
-
Whether the Notification dated 11.10.2000 approving the respondent-Port Trust as custodian under Section 45(1) of the Customs Act is valid, and whether liability for pilfered goods can consequently be fastened upon it under Section 45(3) of the Customs Act?
CONTENTIONS OF THE APPELLANT
-
The Appellant contended that the saving clause contained in Section 45(1) of the Customs Act does not exclude the power of the Commissioner of Customs to approve a person as the custodian of imported goods merely because the custody of such goods is also governed by another statute, namely, the Major Port Trusts Act, 1963.
-
The Appellant argued that the fact that the respondent-Port Trust derives its custody of imported goods under the Major Port Trusts Act does not confer any immunity upon it from the statutory liability to pay customs duty under the Customs Act, 1962.
-
The Appellant further argued that upon being duly approved as a custodian under Section 45(1) of the Customs Act, the respondent-Port Trust becomes liable under Section 45(3) to discharge the customs duty in respect of goods pilfered while in its custody, notwithstanding any other statutory arrangement governing such custody.
-
Furthermore, the Notification dated 11.10.2000 was issued by the Commissioner of Customs in exercise of the express statutory power conferred under Section 45(1) of the Customs Act and, therefore, was neither without jurisdiction nor ultra vires the said provision.
-
The Appellant concluded that the impugned judgment of the High Court, holds that the Commissioner of Customs lacked jurisdiction to issue the Notification dated 11.10.2000, is contrary to the statutory scheme of Section 45 of the Customs Act and is therefore liable to be set aside.
CONTENTIONS OF THE RESPONDENT
-
The Respondent contended that the custody of the imported goods by the respondent-Port Trust is derived from and governed by the provisions of the Major Port Trusts Act, 1963, and not from Section 45(1) of the Customs Act, 1962.
-
The Respondent argued that although Section 45(3) of the Customs Act fastens liability for customs duty on the person approved as custodian under Section 45(1), such liability can arise only where a valid approval under Section 45(1) exists.
-
The Respondent further argued that the Commissioner of Customs had no jurisdiction to approve the respondent-Port Trust as a custodian under Section 45(1), since its custody of imported goods was already governed by the Major Port Trusts Act, 1963.
-
Furthermore, Section 45(3) cannot independently fasten liability upon the respondent when the foundational requirement of a valid approval under Section 45(1) is absent.
-
The Respondent further contended that the Commissioner, in issuing the Notification dated 11.10.2000 and declaring the respondent-Port Trust to be a custodian for the purposes of Section 45(3), acted beyond the jurisdiction conferred upon him by Section 45(1) of the Customs Act.
-
That consequently, the Notification dated 11.10.2000 was without jurisdiction and ultra vires Section 45(1) of the Customs Act, and the High Court was justified in quashing the same.
-
That, in any event, the Notification dated 11.10.2000 could have no retrospective application to instances of pilferage occurring prior to its issuance. Therefore, no customs duty under Section 45(3) could be recovered from the respondent for the pre-notification period.
-
That since the respondent had not been approved as a custodian under Section 45(1) during the period in which the alleged pilferage occurred, the liability contemplated under Section 45(3) could not be fastened upon it in respect of those demands.
JUDGEMENT ANALYSIS
-
Interpretation of Section 45(1) and the Saving Clause: The Court examined the saving clause in Section 45(1), namely “save as otherwise provided in any law for the time being in force.” It states that the saving clause would bar the Commissioner’s Approval only if the other statute itself fastens customs duty on pilfered goods on them. The Court therefore rejected the contention that the Major Port Trusts Act completely excluded the operation of Section 45(1).
-
Section 45(3) Creates an Independent Liability for Customs Duty: The Court held that Section 45(3) creates a specific statutory liability upon the approved custodian to pay customs duty where imported goods are pilfered while in its custody. This provision was introduced by Parliament with effect from 26.05.1995 to prevent loss of revenue, particularly because Section 13 absolves the importer from payment of duty on goods pilfered after unloading and before clearance.
-
Difference Between Liability under the Customs Act and the Major Port Trusts Act: The Court made an important distinction between the two statutory liabilities. Under Section 43 of the Major Port Trusts Act, the Port Trust’s liability is essentially that of a bailee towards the owner of the goods and is compensatory in nature. In contrast, Section 45(3) of the Customs Act creates an independent statutory liability towards the Revenue for payment of customs duty on pilfered imported goods.
-
Overriding Effect of the Non-Obstante Clause in Section 45(3): The Court emphasised that Parliament deliberately incorporated the words “notwithstanding anything contained in any law for the time being in force” in Section 45(3). Therefore, where the requirements of Section 45(3) are satisfied, the liability to pay customs duty prevails notwithstanding the provisions of the Major Port Trusts Act. The Court held that the only essential precondition is that the person must have been approved as custodian under Section 45(1).
-
Section 45(2) Applies Irrespective of the Source of Custody: The Court also considered Section 45(2), which imposes statutory duties upon a person having custody of imported goods in a customs area. These duties include maintaining records of the goods and ensuring that they are not removed or dealt with without the permission of the proper officer. Importantly, these obligations apply whether custody arises under Section 45(1) or under any other law, including the Major Port Trusts Act.
-
Pilferage is Distinct from Ordinary Loss or Destruction: The Court clarified that pilferage and ordinary loss/destruction are legally distinct. The Major Port Trusts Act may govern ordinary loss or destruction of goods, whereas pilferage in a customs area is specifically addressed by the Customs Act. Consequently, the saving clause in Section 45(1) does not prevent the operation of Section 45(3) in cases of pilferage.
-
Validity of the Notification and Effect on Pre-Notification Demands: After considering Sections 45(1), 45(2) and 45(3) together with Sections 42 and 43 of the Major Port Trusts Act, the Supreme Court held that the Commissioner of Customs was fully justified in issuing the Notification dated 11.10.2000 approving Mumbai Port Trust as custodian. The High Court therefore erred in holding the notification to be without jurisdiction and in quashing it.



 > Mon - Sat, 9:00 AM – 7:30 PM